Luxury Villas Market: Lake Maggiore Outperforms European Benchmarks
The Lake Maggiore luxury property market shows consistent 8-12% annual appreciation. Analysis of buyer demographics, price trends, and investment potential.
Lake Maggiore: Italy's Premier Luxury Destination
The Italian Lakes region, and Lake Maggiore in particular, has established itself as one of Europe's most desirable luxury property markets. This analysis examines current trends and future projections.
Market Performance
Price Appreciation (2019-2024)
- •Average annual growth: 9.7%
- •Prime lakefront: 12-15% annually
- •New-build premium: 15-20% over resale
Comparison to European Markets
| Market | 5-Year CAGR |
|---|---|
| Lake Maggiore | 9.7% |
| Lake Como | 8.5% |
| French Riviera | 6.2% |
| Mallorca | 7.8% |
| Algarve | 5.9% |
Buyer Demographics
By Nationality (2024)
- •Swiss: 28%
- •German: 22%
- •UK: 15%
- •Benelux: 12%
- •US: 8%
- •Middle East: 7%
- •Other: 8%
By Purchase Motivation
- •Primary residence: 15%
- •Second home: 55%
- •Investment: 20%
- •Retirement: 10%
Demand Drivers
1. Lifestyle Appeal
- •Mediterranean climate with Alpine proximity
- •Golf, sailing and outdoor activities within a 30-minute drive
- •Michelin-starred dining and wine regions
- •Cultural attractions (museums, festivals, historic sites)
2. Accessibility
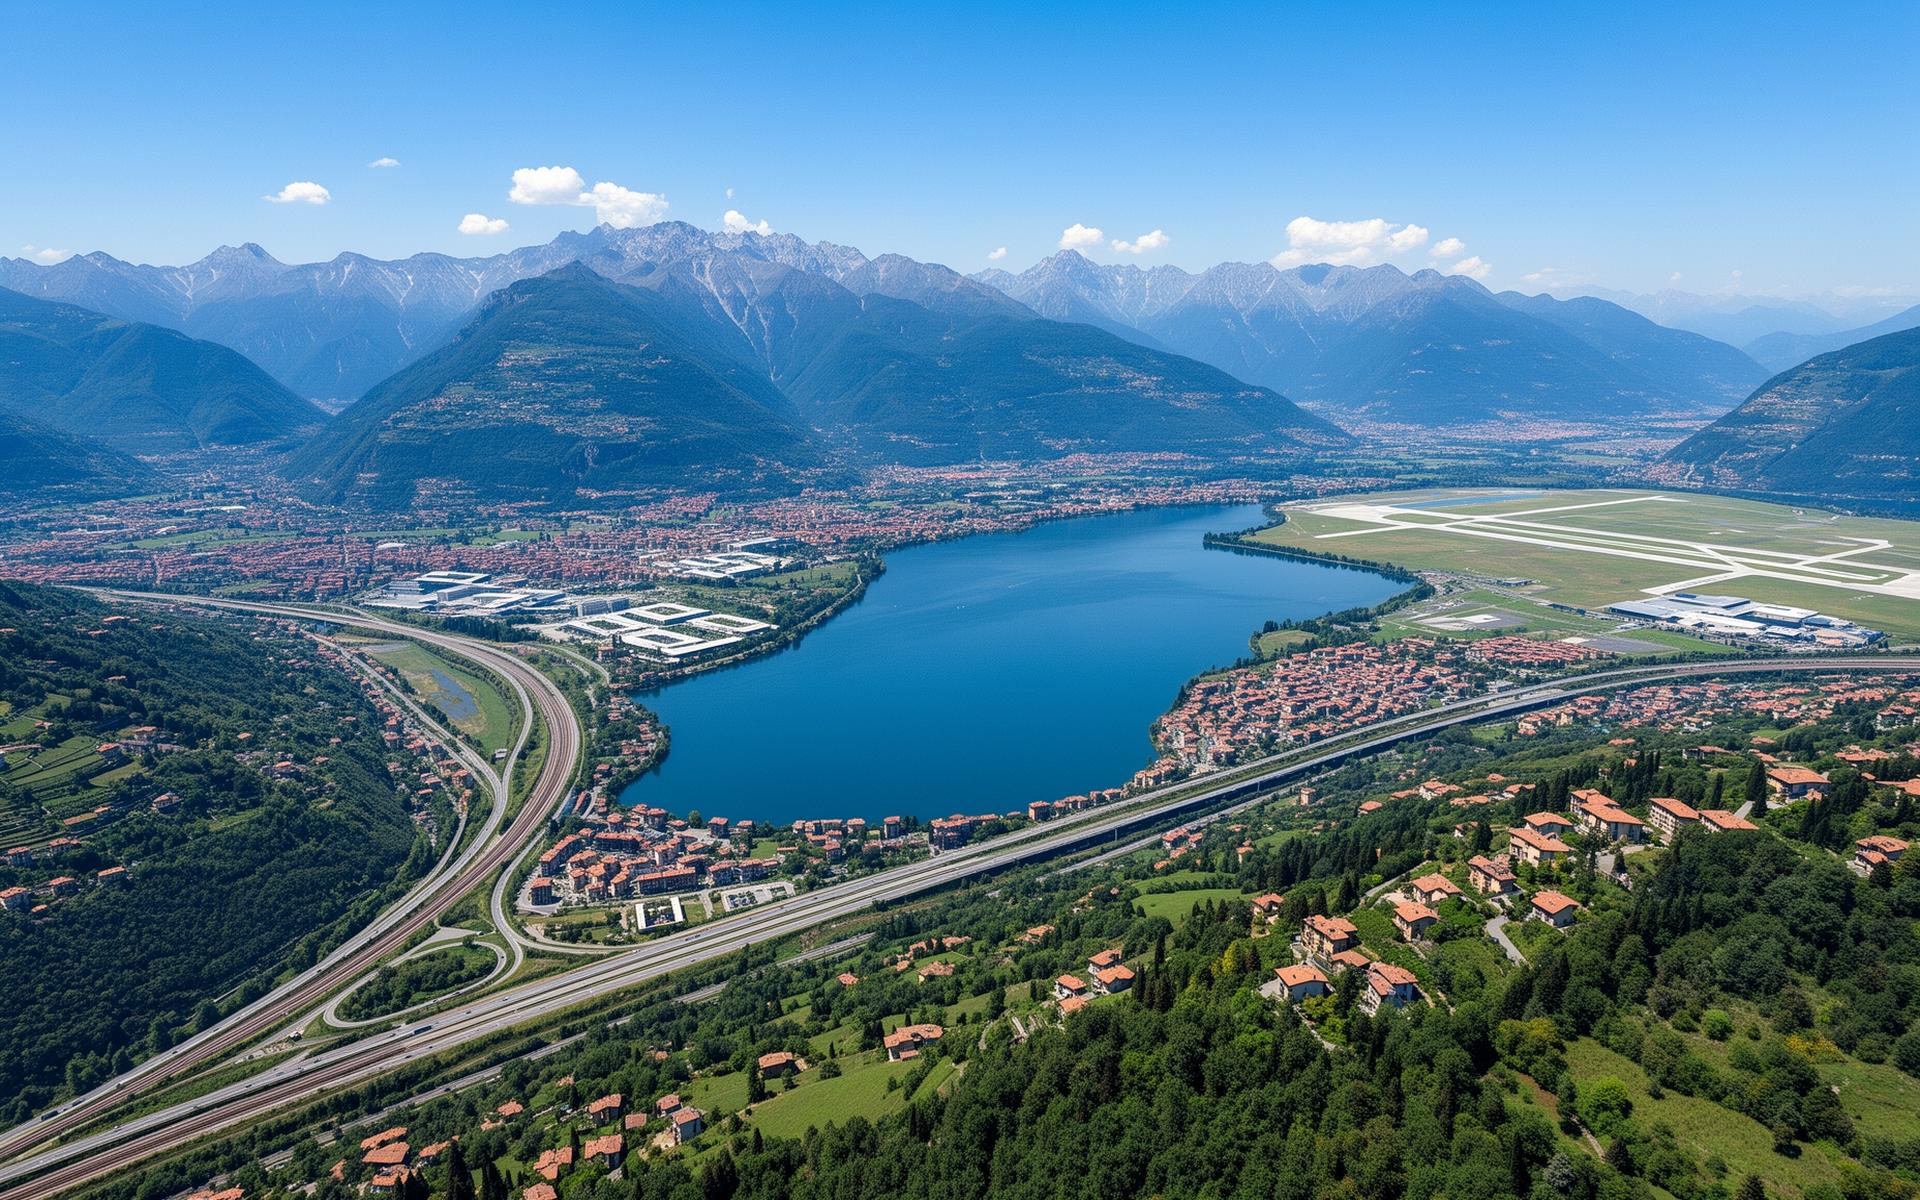
- •Milan Malpensa Airport: 25-40 minutes
- •Swiss border: 30 minutes
- •High-speed rail connections
- •Excellent road infrastructure
3. Value Proposition
- •30-40% lower than Lake Como prime prices
- •Superior value per square meter vs. French Riviera
- •Lower property taxes than Switzerland
- •Favorable inheritance laws for non-residents
Supply Constraints
Limited new development maintains value:
- •Protected landscape designations
- •Stringent planning regulations
- •High-quality construction standards
- •Limited suitable land parcels
Our Villas Offering
Futuro Agrate provides rare new-build opportunity:
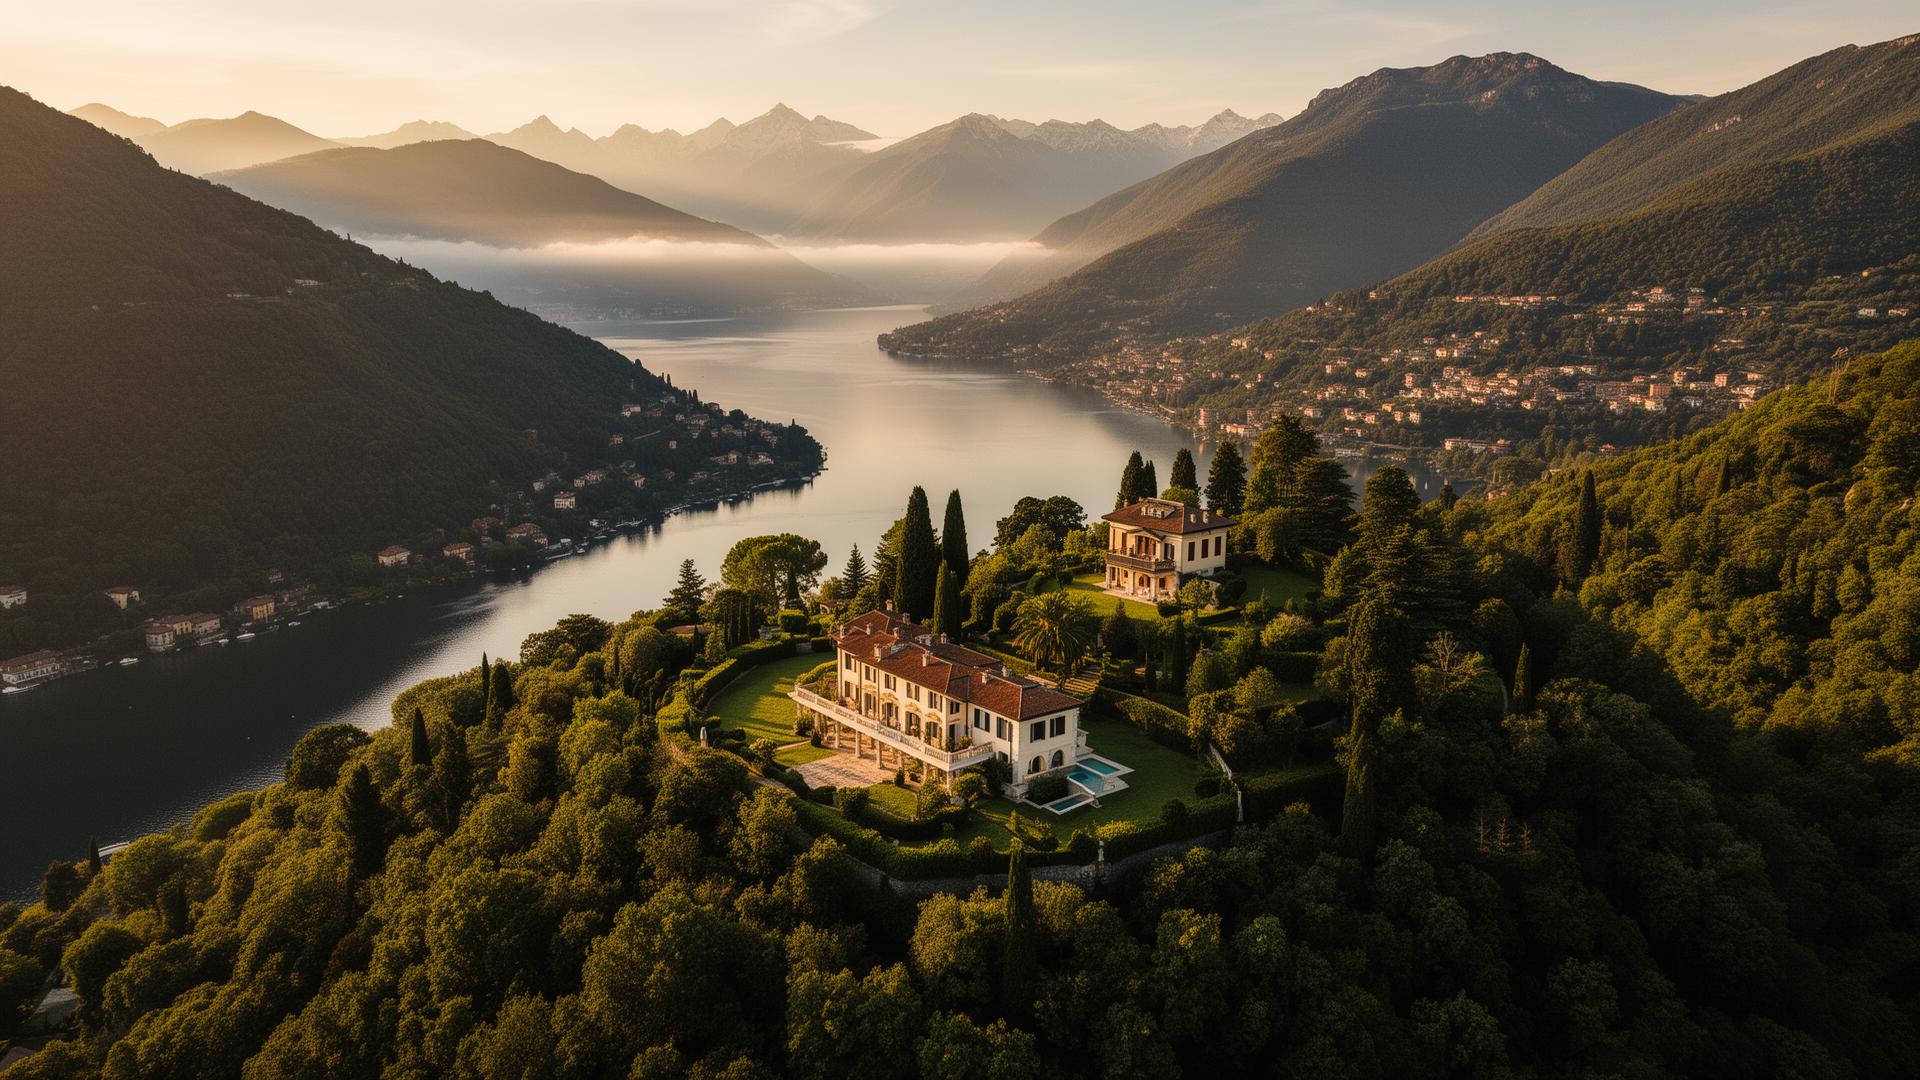
- •36 luxury villas with approved permits
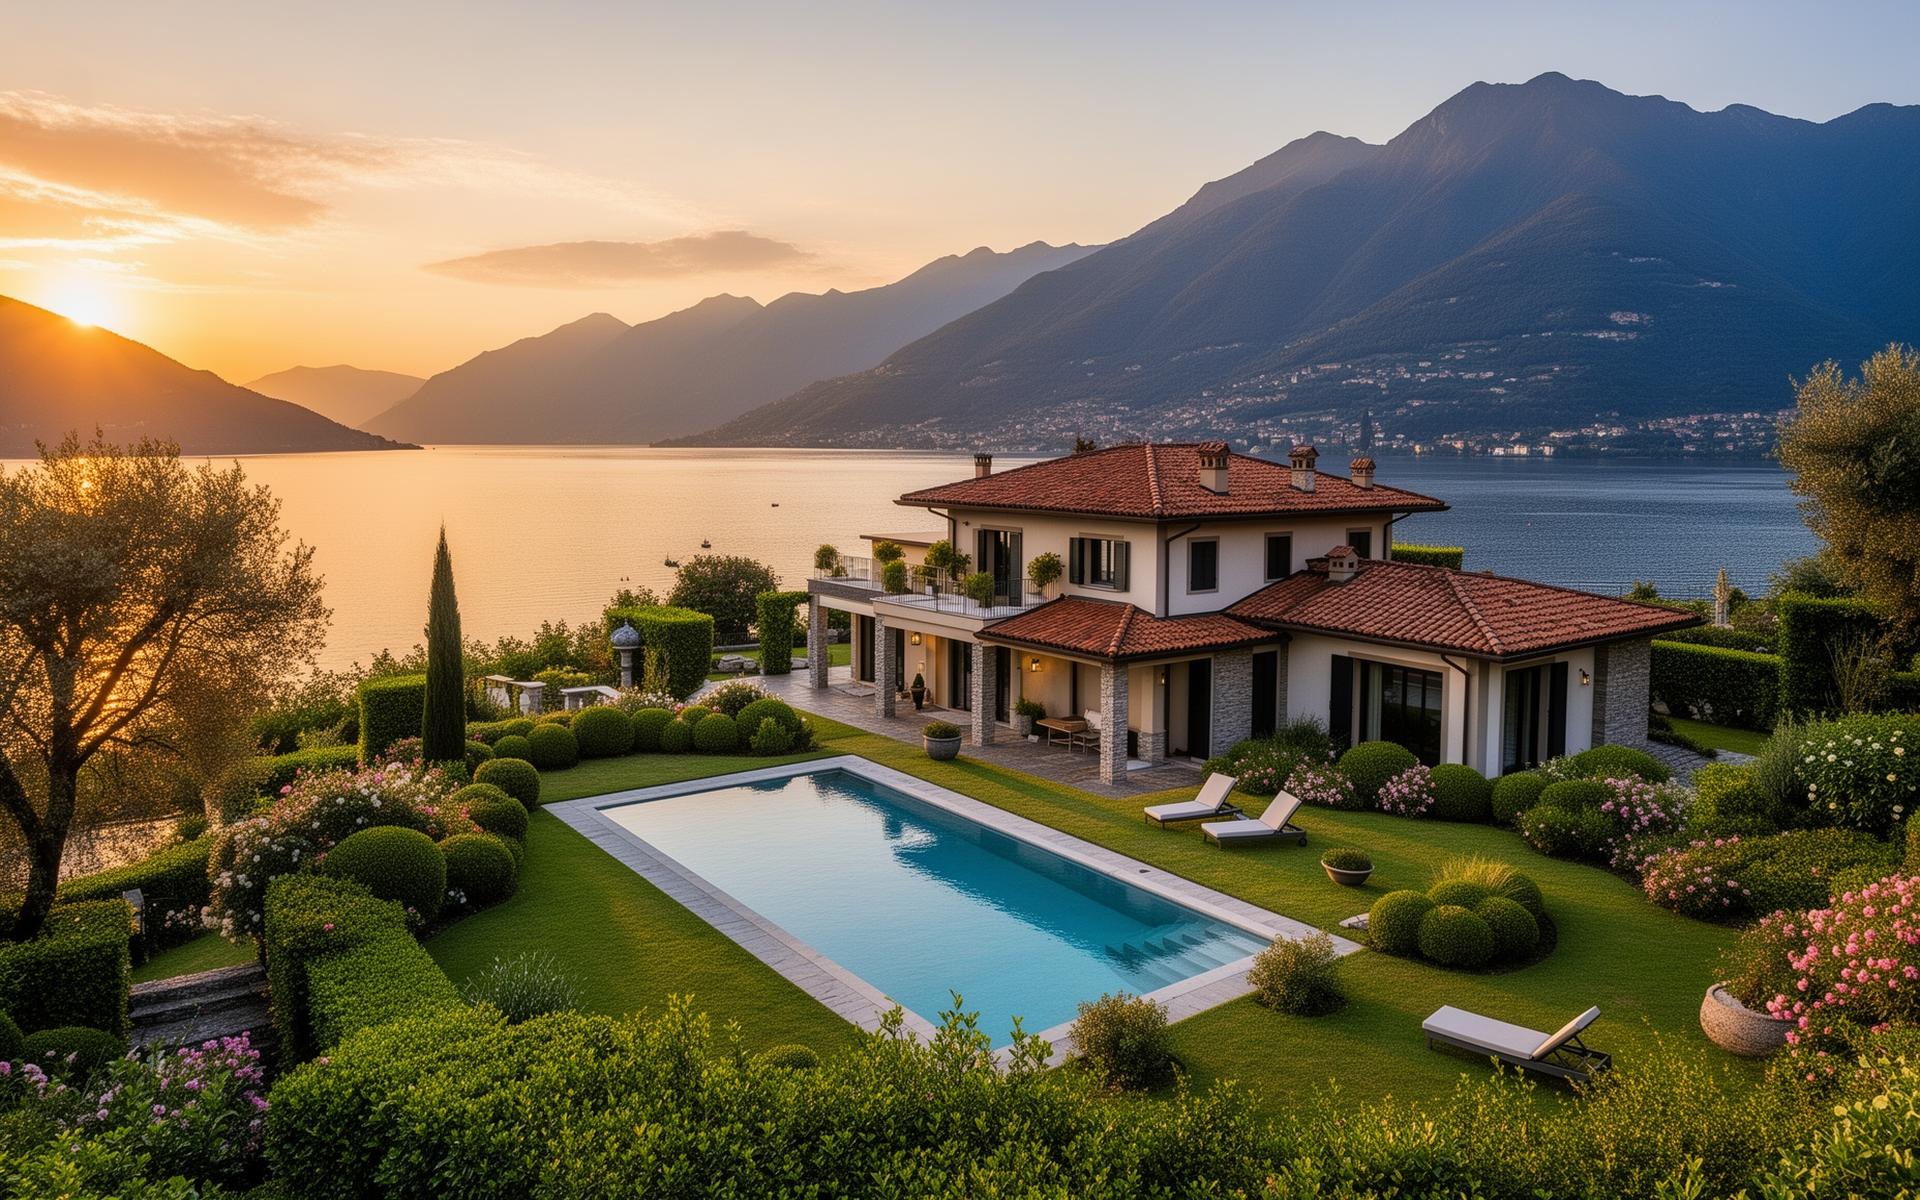
- •Private pools and gardens
- •Views of Monte Rosa and surrounding peaks
- •Golf course access within the territory
- •5-star hotel and spa services available
Price Points (Starting)
- •3-bedroom villa: from €950,000
- •4-bedroom villa: from €1,350,000
- •Premium positions: from €1,800,000
Investment Returns
Expected performance metrics:
- •Capital appreciation: 8-12% annually
- •Rental yield (if let): 4-6% gross
- •Total return potential: 12-18% annually
Buyer Journey
- •Enquiry — Initial consultation and qualification
- •Viewing — Site visit and villa selection
- •Reservation — Preliminary agreement with deposit
- •Completion — Final contract and registration
Editorial note: this article is for information purposes and does not constitute investment advice.
Sources and verification
Primary sources consulted
- Agenzia delle Entrate — OMI — Osservatorio del Mercato Immobiliare, half-yearly quotations agenziaentrate.gov.it
- Nomisma — Osservatorio sul Mercato Immobiliare
- Knight Frank — The Wealth Report, prime residential indices
- Savills Research — European residential and second-home market reports
Figures presented as ranges, uplifts or returns are model estimates based on the sources below. They are not measurements of this site and not a promise of performance.
Read the Journal by interest rather than by publication date. Each path is a sequence, not an archive.
The regional brief
5 articlesNorthern Italy read as a residential and investment region rather than as a holiday destination.
You are here · Step 3 of 5
- 1Northern Italy as a European Residential and Investment Region
- 2The Milan–Lake Maggiore–Swiss CorridorIn research
- 3Why Piedmont Remains Less Expensive Than Better-Known Italian Regions
- 4Climate, Landscape and Year-Round Liveability in Northern ItalyIn research
- 5Can Piedmont Become a Global Lifestyle Destination?
The investor journey
8 articlesFrom how development value is created before construction to how integrated schemes are underwritten.
- 1How Land Consolidation Creates Development Value
- 2Why Planning Rights Can Be More Valuable Than Construction
- 3Senior Secured Development Finance Explained
- 4How Institutional Investors Assess Integrated Developments
- 5Why Phasing Matters More Than the Final Masterplan
- 6Does Combining Residential, Hospitality, Wellness and Sport Actually Work?
- 7What Can Go Wrong in a Multi-Use Lifestyle Development?In research
- 8The Integrated Community as a Long-Term Investment and Living ModelIn research
The living journey
8 articlesWhat changes in how people want to live, and what a low-density community must deliver in return.
- 1Why Affluent Households Are Reconsidering Large-City LivingIn research
- 2Luxury Is Becoming Time, Privacy and ConvenienceIn research
- 3The Rise of the 15-Minute Lifestyle Beyond the CityIn research
- 4Why Nature Is Becoming an Economic AssetIn research
- 5From Second Home to Second LifeIn research
- 6How Far Are People Actually Willing to Walk?In research
- 7Why Residential Value Depends on Everything Outside the Home
- 8How a Large Estate Can Feel IntimateIn research
The operator journey
7 articlesDemand, seasonality and critical mass for hospitality, wellness, sport and food & beverage.
- 1Why Hospitality Can Accelerate Residential Demand
- 2Can Hotels and Permanent Residents Successfully Share One Destination?In research
- 3The Economics of a Food and Beverage EcosystemIn research
- 4From Spa to Everyday WellnessIn research
- 5Who Pays for Wellness and Why?In research
- 6Can Sport Reduce Seasonality?
- 7How Much Population Does an Integrated Community Need?In research
Why Northern Italy
Article 3 of 5The Milan–Lake Maggiore–Swiss Corridor
Climate, Landscape and Year-Round Liveability in Northern Italy